 News & Media
How to afford mental health care: financing options explained
Struggling to afford mental health care? Explore insurance coverage, real costs, sliding scale options, and financing strategies for integrative and holistic…
Kabir Ali
 10 min read
TL;DR:
- Many Americans face high out-of-pocket costs despite mental health coverage.
- In-network therapy is usually more affordable, and sliding scale fees can reduce expenses.
- Alternative financing methods like payment plans, loans, and public programs help access holistic treatments.
Despite more coverage for mental health care than ever before, millions of Americans still struggle to pay for therapy, holistic treatments, and integrative care. All Marketplace plans are required to cover mental health and substance abuse services, yet gaps in coverage, high deductibles, and out-of-pocket costs leave many people feeling stuck before they even start. If you’ve ever looked at a therapy bill and felt your heart sink, you’re not alone. This guide walks you through the full picture, from insurance basics to creative financing strategies, so you can find a path to the care you actually need, including holistic and integrative options.
Key Takeaways
- 01
Insurance covers basics
Most insurance plans cover standard mental health treatment, but not all integrative therapies.
- 02
Out-of-pocket costs vary
Therapy, medication, and holistic care costs differ widely by provider, insurance, and treatment type.
- 03
Low-cost options exist
Sliding scales, grants, and community clinics help make care affordable for those without insurance.
- 04
Alternative financing available
Payment plans, loans, and crowdfunding can bridge the gap when insurance or free programs aren’t enough.
- 05
Combine strategies
Blending multiple options and advocating for your needs maximizes your access to affordable care.
Understanding insurance coverage for mental health care
Let’s start by clearing up what your insurance actually covers, because the details matter more than most people realize. The good news is that mental health coverage is required as an essential health benefit under the Affordable Care Act for all Marketplace plans. That means therapy, counseling, and substance abuse treatment must be included. Pre-existing mental health conditions cannot result in higher premiums or denial of coverage.
Medicare covers outpatient and inpatient behavioral health services, including opioid disorder treatment. Medicaid also includes behavioral health benefits, though the specifics vary by state. Both programs have made real progress, but they still tend to lag when it comes to integrative approaches like ketamine-assisted therapy or mindfulness-based programs.
The Mental Health Parity and Addiction Equity Act is a federal law that requires insurers to treat mental health benefits comparably to physical health benefits. In plain terms, your insurer cannot impose stricter limits on therapy visits than they would on, say, physical therapy sessions. This law has teeth, but it doesn’t always get enforced the way it should.
Here’s a quick comparison of what different plan types typically cover:
| Plan type | Therapy | Medication | Integrative/holistic |
|---|---|---|---|
| ACA Marketplace | Yes | Yes | Rarely |
| Medicare | Yes | Partial | Rarely |
| Medicaid | Yes | Yes | Rarely |
| Employer-sponsored | Yes | Yes | Sometimes |
| Private/self-pay | N/A | N/A | Yes |
Some key things to check when reviewing your coverage details:
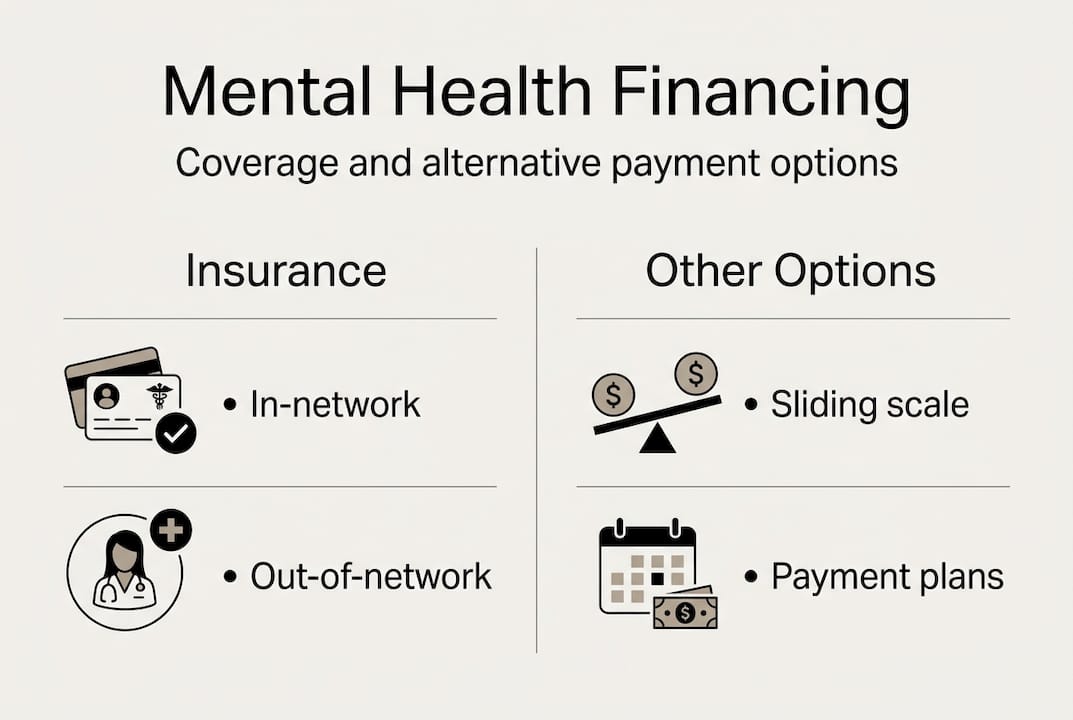
- Whether your therapist is in-network or out-of-network
- Your annual deductible and out-of-pocket maximum
- Whether prior authorization is required for certain treatments
- If telehealth mental health services are covered
The most common mistake people make is assuming their plan covers everything. Always call your insurer directly and ask specific questions about the treatment you’re seeking.
Ketamine therapy, which is prescribed off-label, and many holistic treatments are largely out of pocket for now. Spravato (esketamine), which is FDA-approved for depression, is a different case: most major plans have a path to cover it once criteria are met. Knowing your baseline coverage helps you plan for the gaps.
Estimating costs: What does mental health care really cost?
Understanding your coverage is only half the equation. You need to know what you’ll actually pay out of pocket, because the numbers can be surprising.
Health Care Cost Institute data on therapy spending show that people with employer insurance who use therapy can spend a substantial amount on it each year, and that what you pay depends heavily on copays, deductibles, and whether your therapist is in network. Meanwhile, family health premiums averaged $26,993 in 2025, a number that reflects just how much of your budget goes toward coverage before you’ve even booked a session.
Here’s a general picture of how costs tend to work for different types of care. Exact prices vary widely by provider, plan, and region:
| Type of care | In-network cost | Out-of-network cost | Self-pay (no insurance) |
|---|---|---|---|
| Individual therapy (per session) | Copay or coinsurance | Higher; partial reimbursement possible with a superbill | Full session fee |
| Psychiatric evaluation | Copay or coinsurance | Higher; partial reimbursement possible | Full evaluation fee |
| Spravato (esketamine) | Often covered, with prior authorization | Depends on plan | Rarely needed if covered |
| Ketamine-assisted therapy | Rarely covered (off-label) | A superbill may recover part | Usual route |
| Holistic/integrative session | Sometimes, if billed as a medical visit | Rarely covered | Common |
| Medication management | Copay or coinsurance | Higher; partial reimbursement possible | Full visit fee |
For reference, at Mystic psychotherapy is $199–299 an hour and psychiatry is $499 a session, and many plans cover both. A ketamine session is $500, with packages listed on our pricing page.
Out-of-network costs hit especially hard. The same therapy spending data show that people pay considerably more out of pocket for out-of-network therapy than for in-network care. Choosing an in-network provider when possible can be one of the most impactful financial decisions you make.
For holistic and integrative services, self-pay is often the norm. This is where knowing your total out-of-pocket maximum becomes important. On most plans, once you reach that ceiling, your insurer pays the full cost of covered in-network services for the rest of the plan year.
Pro Tip
Many therapists and integrative clinics offer sliding scale fees, meaning they adjust their rate based on your income. It’s worth asking directly, even if it feels awkward. Most providers would rather work with you than lose you as a patient.
If you’re comparing treatment options, always ask for a Good Faith Estimate before committing. Federal law requires providers to give you one if you’re uninsured or paying out of pocket.
Free, low-cost, and sliding scale options
If your costs still feel out of reach, or you lack insurance entirely, there are real ways to access quality care without going into debt.
SAMHSA, the Substance Abuse and Mental Health Services Administration, is one of the most underutilized resources in the country. They offer a treatment locator, information on sliding scale programs, grants, and scholarships specifically for mental health and substance use care. Their helpline is free, confidential, and available 24/7.
Here are the main low-cost and free options worth exploring:
- Community mental health centers: Federally funded clinics that offer therapy, psychiatry, and crisis services on a sliding scale based on income
- Medicaid and CHIP: If your income qualifies, these programs can cover a wide range of mental health services at little to no cost
- Employee Assistance Programs (EAPs): Many employers offer a limited number of free short-term counseling sessions through EAPs
- University training clinics: Graduate students in supervised programs offer therapy at significantly reduced rates
- Nonprofit organizations: Groups focused on specific conditions, like anxiety or PTSD, sometimes offer grants or free counseling
- Peer support groups: Peer support networks can provide meaningful emotional support alongside or between professional sessions
Free or low-cost treatment through SAMHSA-connected programs often excludes holistic or self-pay integrative options. That’s a real limitation. But combining a community clinic for traditional therapy with a sliding scale integrative provider for holistic work is a strategy more people use than you’d think.
Pro Tip
When calling a clinic, ask specifically: “Do you offer sliding scale fees, and what documentation do I need to qualify?” Many clinics don’t advertise this openly, but they do offer it.
For those exploring integrative mental health resources, it’s worth asking providers directly about income-based pricing. The integrative space is evolving quickly, and some clinics are actively working to make access more equitable.
Alternative financing: Payment plans, loans, and creative strategies
Beyond insurance and public programs, a range of alternative financing methods can bridge the gap for holistic or uncovered treatments. This is where many people find the most flexibility.
It’s worth noting that many US adults with mental health conditions don’t receive treatment, and people without insurance are less likely to get care. Financial barriers are a real driver of that gap.
Here are practical steps for pursuing alternative financing:
- Ask your provider about a payment plan. Many clinics, especially integrative ones, will let you spread costs over several months with no interest. Ask before assuming it’s not available.
- Look into medical credit cards. Cards like CareCredit offer deferred interest periods for healthcare expenses. Read the fine print carefully to avoid surprise charges.
- Consider a personal loan. For larger treatment programs like ketamine-assisted therapy, a personal loan through a credit union often carries lower interest than medical credit cards.
- Explore crowdfunding. Platforms like GoFundMe have been used successfully for mental health treatment costs. Be specific about what you need and why, and share your story honestly.
- Check for HSA or FSA eligibility. Health Savings Accounts and Flexible Spending Accounts can sometimes be used for mental health treatments, including some integrative therapies, if a licensed provider prescribes them.
Crowdfunding works best when you’re transparent and specific. Vague requests rarely gain traction. Sharing your genuine story, without oversharing, tends to resonate most.
For those researching financing for alternative treatments, payment plans are increasingly common at integrative clinics. The key is to ask early in the intake process, not after you’ve already committed.
Creative financing isn’t a sign of desperation. It’s a sign that you’re serious about your healing and willing to show up for yourself in practical ways.
Why financing mental health care requires thinking outside the box
Here’s what most guides won’t tell you: no single financing path works for everyone, and the people who actually access the care they need are usually the ones who build a patchwork strategy.
Conventional advice points you toward insurance first, then public programs, then personal resources. But in practice, many people are using all three at once. Someone might use insurance for traditional therapy, SAMHSA resources for crisis support, and a payment plan for ketamine-assisted sessions. That’s not a workaround. That’s smart, intentional planning.
Insurance coverage tends to follow evidence and FDA approval over time. Spravato is an example: once it was approved, most major plans created a path to cover it. You can review the clinical evidence behind newer treatments. Advocating for coverage with your insurer, asking your HR department about integrative benefits, and documenting your treatment outcomes all contribute to a broader shift.
Pro Tip
Don’t accept the first “not covered” response from your insurer. Ask for the specific policy language, ask whether your provider can request a peer-to-peer review, and file an appeal if necessary. Some denials are overturned on appeal.
Your financing strategy is part of your healing strategy. Treat it with the same care and intention.
Explore holistic care backed by flexible financing
If this guide has helped you see that access to mental health care, including integrative and holistic therapies, is more within reach than you thought, we’d love to help you take the next step.
At Mystic Health, we offer integrative care including psychotherapy, psychiatry, integrative medicine, Spravato, and ketamine-assisted psychotherapy. We check your benefits for free, prepare Spravato prior authorizations, provide superbills for out-of-network benefits, and offer financing for ketamine therapy, so cost doesn’t have to be the reason you don’t start. Whether you’re just beginning to explore or you’re ready to commit, our team is here to walk alongside you. Start with a free benefits check and let’s find what works for you.
Frequently asked questions
Does insurance cover psychedelic-assisted therapy or holistic treatments?
Most plans do not cover ketamine therapy, which is prescribed off-label, or most holistic treatments, though a superbill may recover part of the cost if you have out-of-network benefits. Spravato is different: it is FDA-approved for depression and often covered once criteria are met, usually with prior authorization. Psilocybin and MDMA are not approved treatments, so insurance does not cover them.
What should I do if I can’t afford therapy out of pocket?
Explore SAMHSA-funded clinics, sliding scale providers, and nonprofit grants first, then ask your provider directly about payment plans before assuming care is out of reach.
How do out-of-network mental health costs compare to in-network?
Out-of-network therapy usually costs considerably more out of pocket than in-network care, so choosing an in-network provider can cut your costs substantially. If you prefer an out-of-network therapist, a superbill may let you recover part of the fee.
Are there financing options for mental health if I am uninsured?
Yes. Community clinics, SAMHSA, and sliding scale providers all offer pathways to care for uninsured individuals, and many clinics also offer payment plans regardless of insurance status.
Can payment plans or loans pay for integrative or experimental therapies?
Yes, many integrative clinics offer in-house payment plans, and personal or medical loans can be used to cover non-traditional therapies that insurance doesn’t include.
Recommended
 Sources and references (6)

- 1.All Marketplace plans healthcare.gov
- 2.Medicare covers outpatient and inpatient medicare.gov
- 3.Health Care Cost Institute data on therapy spending healthcostinstitute.org
- 4.family health premiums ehbs.kff.org
- 5.SAMHSA samhsa.gov
- 6.Free or low-cost treatment samhsa.gov
This article is for educational purposes only and does not constitute medical advice, diagnosis, or treatment. Always consult a qualified healthcare provider about your own care.
Questions about coverage?
Our team can help you understand your options and build a plan that fits your values.
Schedule a consultation